Moove’s decision to withdraw from Nigeria has exposed a significant weakness in the business model used by mobility financing companies, where the ability of drivers to repay vehicle loans depends heavily on the continued operation of ride-hailing platforms.
The Lagos-founded company announced on Thursday that it would discontinue its Nigerian operations after six years, transferring vehicles valued at approximately N35 billion to eligible customers as part of its exit arrangements.
The development follows Uber’s withdrawal from Nigeria in September, which removed a major source of passenger bookings and driver earnings supporting Moove’s local vehicle-financing operations.
For a company whose business involves providing vehicles to drivers who generate income through ride-hailing services, the loss of a major operating platform creates consequences extending beyond passenger demand.
It affects the income available for vehicle repayments, the commercial viability of financing arrangements and the ability to maintain a predictable flow of revenue from financed assets.
Moove co-founder and co-chief executive officer Ladi Delano confirmed that Uber had been central to the company’s Nigerian operations.
In an interview with BusinessDay, Delano explained that the company examined alternative arrangements following Uber’s departure but concluded that continuing its existing Nigerian business was no longer commercially sustainable.
The decision brings an end to Moove’s operations in the country where it was established in 2020 by Delano and Jide Odunsi.
The company initially entered the market to address a financing challenge facing commercial drivers who could generate income from transportation services but lacked sufficient capital to purchase vehicles.
Its business model allowed qualifying drivers to access vehicles through rental and drive-to-own arrangements, with payments structured around income generated from commercial transportation activities.
That approach created opportunities for individuals who might otherwise have struggled to secure conventional vehicle financing.
However, it also connected the performance of the financing business to the financial health of the ride-hailing market.
Unlike conventional vehicle lenders that may finance customers with income from several unrelated sources, mobility financing providers can have significant exposure to earnings generated through specific transportation platforms.
When those platforms experience declining demand, change their operating conditions or leave a market entirely, the effect can extend to the financing companies supplying vehicles to their drivers.
Uber’s departure therefore represented more than the loss of a commercial partner for Moove.
It disrupted an important part of the operating structure through which financed vehicles generated revenue.
The development raises questions for investors about the risks associated with financing assets whose repayment capacity depends on third-party digital platforms.
Such arrangements can expand access to financing by using operating income to support repayments, but they also create exposure to business decisions outside the lender’s direct control.
Moove’s response has been to discontinue its Nigerian operations while transferring ownership of eligible vehicles to the customers currently operating them.
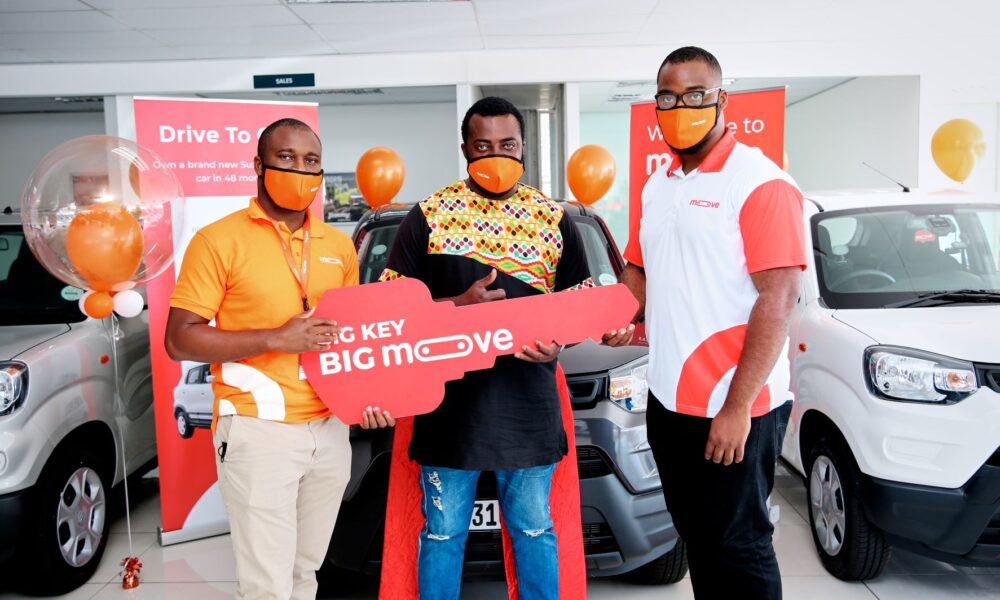
Under the company’s Thank You Nigeria initiative, vehicles with an estimated combined value of N35 billion will pass into the ownership of qualifying customers.
Moove said no further scheduled vehicle payments would be required from October 1, 2026, although eligible customers must settle outstanding remittances relating to periods before that date and complete the necessary transfer procedures.
The distinction is important because the arrangement does not necessarily eliminate every outstanding obligation associated with a customer’s previous use of a vehicle.
Instead, it brings forward ownership for qualifying drivers while ending future scheduled payments to Moove for the vehicles themselves.
For affected drivers, the arrangement could significantly change their financial position.
Drivers who previously made regular payments under vehicle-financing agreements may now be able to retain a greater proportion of their transportation earnings after satisfying the conditions of the ownership transfer.
However, they will remain responsible for the commercial realities of operating vehicles, including fuel, maintenance, insurance and other expenses.
Their ability to generate sustainable income will also depend on access to alternative passenger-booking platforms and the demand available in their operating locations.
The company disclosed that more than 9,000 customers had used its rental and drive-to-own products in Nigeria since its establishment.
It estimated that those customers generated approximately N57 billion in revenue through Moove-financed vehicles.
That figure represents earnings associated with customers’ use of the vehicles, rather than Moove’s corporate revenue or profit.
The distinction matters when assessing the company’s contribution to commercial transportation and the financial implications of its withdrawal.
Moove has not publicly disclosed the total outstanding financing receivables being relinquished through the vehicle transfer, the carrying value of the affected assets or the accounting impact of the Nigerian exit.
Consequently, the estimated N35 billion value of the vehicles should not automatically be interpreted as a N35 billion loss to the company.
The financial effect will depend on the vehicles’ book values, outstanding customer obligations, previous collections and the terms of any related financing arrangements.
Beyond the immediate transfer, the withdrawal highlights a wider question about the sustainability of asset-backed financing in Nigeria’s mobility sector.
Commercial drivers face operating costs that can change rapidly, particularly when petrol prices, vehicle maintenance expenses and financing costs increase.
For financing companies, repayment structures must remain affordable enough for drivers to continue operating while generating sufficient returns to cover the cost of capital, asset depreciation and other business expenses.
If the relationship between driver earnings and financing obligations becomes unsustainable, the risk can affect both customers and the institutions providing the vehicles.
Moove’s Nigerian exit illustrates how those pressures can become more difficult to manage when a major platform supporting customer earnings leaves the market.
The development also carries implications for other mobility companies considering expansion into vehicle financing.
A financing model built around one dominant booking platform may offer operational advantages while that platform remains active, but it can create concentration risk when the underlying commercial relationship changes.
Diversifying the sources of customer earnings, maintaining flexibility in repayment structures and assessing the resilience of drivers’ operating margins could become increasingly important considerations for investors in the sector.
Despite leaving Nigeria, Moove is continuing its international operations.
The company said its global business now includes approximately 42,000 vehicles operating across 29 cities, reflecting the expansion of the model beyond the market where it was originally developed.
Its international activities also include a growing focus on autonomous mobility, alongside its existing vehicle-financing operations.
The contrast between Moove’s Nigerian withdrawal and its continued international expansion demonstrates that a business model can remain commercially attractive in some markets while becoming difficult to sustain in others.
For Nigeria’s technology and mobility sectors, the immediate impact is the loss of a company that helped expand access to commercial vehicle financing.
For investors, the larger lesson concerns the relationship between financing businesses and the digital platforms on which their customers depend.
Moove’s departure shows that providing access to productive assets is only one part of building a sustainable financing business.
The more difficult challenge is ensuring that the income supporting those assets remains sufficiently stable to sustain customers, lenders and investors when market conditions change.